The mortgage lender market comprises financial institutions and specialized lending companies that provide loans to individuals and businesses for purchasing, refinancing, or developing real estate. These lenders include commercial banks, mortgage companies, credit unions, and other financial service providers offering home financing solutions. Market growth is influenced by housing demand, urbanization, changing homeownership patterns, and the availability of mortgage products. Digital lending platforms, automated underwriting, and improved loan processing systems are also transforming how lenders evaluate applications and serve borrowers.
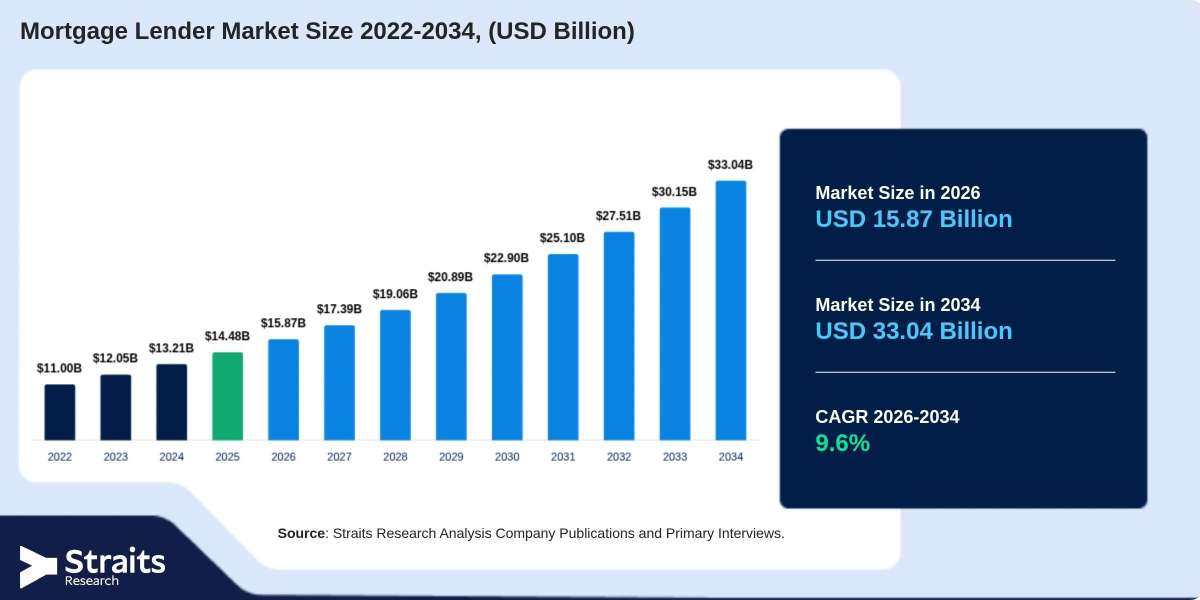
According to Straits Research, the global mortgage lender market size was valued at USD 14.48 billion in 2025 and is projected to grow from USD 15.87 billion in 2026 to USD 33.04 billion by 2034, registering a CAGR of 9.6% during the forecast period from 2026 to 2034. North America dominated the mortgage lender market with a market share of 38.6% in 2025, supported by an established mortgage financing system, demand for residential properties, and the presence of major financial institutions and mortgage service providers.
Get Full Report: https://straitsresearch.com/report/mortgage-lender-market
Rising Housing Demand Fuels Mortgage Lending Growth
Population growth, household formation, and urbanization are contributing to demand for residential properties in many markets. For individuals who cannot purchase homes outright, mortgage financing provides a way to spread the cost of homeownership over an extended period. This creates opportunities for banks, mortgage companies, and other lending institutions to serve first-time buyers, existing homeowners, and property investors.
Housing demand also encourages lenders to develop products for different borrower profiles, including fixed-rate mortgages, adjustable-rate loans, and specialized home financing options. However, affordability, property prices, and borrowing costs influence the ability of households to qualify for financing. The ongoing need for housing and long-term property finance is expected to support market growth.
Digital Mortgage Platforms Improve Lending Efficiency
Digital transformation is changing how mortgage lenders attract customers, process applications, and manage loan documentation. Online platforms allow borrowers to submit applications, upload financial records, compare available products, and monitor application progress without relying entirely on in-person interactions. These capabilities can simplify the mortgage process and improve accessibility for customers.
Lenders are also adopting automated document verification, digital identity checks, and data-driven underwriting tools to reduce manual processing. Better integration between application systems and loan management platforms can help improve operational efficiency and communication with borrowers. Continued investment in digital lending technology is expected to support market development.
Government Housing Initiatives and Mortgage Accessibility Support Demand
Government housing policies and financing initiatives can influence mortgage market activity by improving access to homeownership and supporting eligible borrowers. Programs such as down-payment assistance, housing subsidies, and targeted mortgage guarantees may help some households overcome barriers to obtaining residential financing. Their impact varies according to national policies, eligibility requirements, and economic conditions.
Regulatory frameworks also shape how lenders assess creditworthiness, disclose loan terms, and manage lending risks. Clear consumer protection rules and responsible underwriting practices can support confidence in mortgage financing. As governments and financial institutions respond to housing affordability challenges, housing-related financing initiatives are expected to influence market demand.
Competitive Mortgage Products Expand Borrower Options
Mortgage lenders compete by offering different interest-rate structures, repayment periods, down-payment requirements, refinancing options, and customer service experiences. Borrowers compare these features when selecting a lender, making pricing transparency and clear loan terms important factors in the decision-making process. Lenders that serve specific borrower groups may also differentiate themselves through tailored eligibility criteria and specialized products.
Refinancing creates additional opportunities when borrowers seek to adjust their repayment terms, consolidate eligible debt, or obtain more suitable financing arrangements. Demand for refinancing depends on interest-rate movements, property values, borrower equity, and individual financial circumstances. The availability of diverse mortgage products is expected to support competition and market activity.
Automation and Data Analytics Strengthen Risk Assessment
Mortgage lenders rely on accurate assessments of borrower income, credit history, existing debt, and property value to determine lending eligibility. Data analytics and automated underwriting tools can help lenders evaluate applications more consistently and identify potential risks. These technologies may also support faster decision-making when reliable data and appropriate controls are available.
Advanced risk management is particularly important because mortgage loans typically involve large amounts of capital and long repayment periods. Lenders must account for changes in employment, interest rates, property prices, and borrowers' ability to make payments. Continued investment in analytical tools and risk management systems is expected to support more efficient mortgage operations.
Urbanization and Emerging Borrower Segments Create Opportunities
Urbanization and changing household structures are shaping demand for residential financing in both established and developing markets. Growing cities require housing for workers, families, and new residents, creating opportunities for mortgage lenders to serve a broader range of customers. First-time homebuyers and households moving to larger or more suitable properties represent potential sources of demand.
However, lenders must adapt their products to local income levels, housing costs, credit systems, and regulatory requirements. Flexible application processes and accessible digital services may help financial institutions reach underserved borrower segments where suitable infrastructure and credit information are available. Expanding access to responsible mortgage financing is expected to create further market opportunities.
Regional Analysis Highlights North America's Leading Position
North America dominated the mortgage lender market with a 38.6% share in 2025. The region benefits from established mortgage financing infrastructure, a broad range of lending institutions, and well-developed systems for property transactions and loan servicing. Mortgage products support home purchases, refinancing, and other residential property financing needs across different borrower categories.
The region's market is influenced by interest rates, home prices, household income, credit availability, and broader economic conditions. Lenders are also investing in digital applications, automated underwriting, and online customer services to improve efficiency and borrower experience. Continued demand for housing finance and innovation in mortgage services are expected to support the region's market position.
Europe Benefits from Established Housing Finance Systems
Europe represents an important market for mortgage lenders, supported by established banking systems and demand for residential property financing. Mortgage products vary across countries according to interest-rate structures, housing policies, lending practices, and consumer preferences. Financial institutions serve first-time buyers, existing homeowners, and customers seeking to refinance or change their financing arrangements.
Economic conditions and housing affordability remain important factors influencing mortgage demand across the region. Lenders must also respond to regulatory requirements and evolving expectations for digital financial services. Improvements in online mortgage applications and loan administration may help institutions streamline operations and strengthen customer engagement.
Asia Pacific Offers Opportunities Through Urbanization and Housing Demand
Asia Pacific presents growth opportunities as urbanization, household formation, and economic development influence demand for residential housing. In markets where homeownership is a major financial goal, mortgage lending can help households finance property purchases over longer repayment periods. Banks and other financial institutions are expanding digital services to improve application access and customer convenience.
Market development differs considerably across countries because of variations in income levels, property prices, credit infrastructure, and government housing policies. Lenders must adapt their products and risk assessment practices to local financial conditions. As mortgage access and digital financial services evolve, the region is expected to offer opportunities for lenders targeting suitable borrower segments.