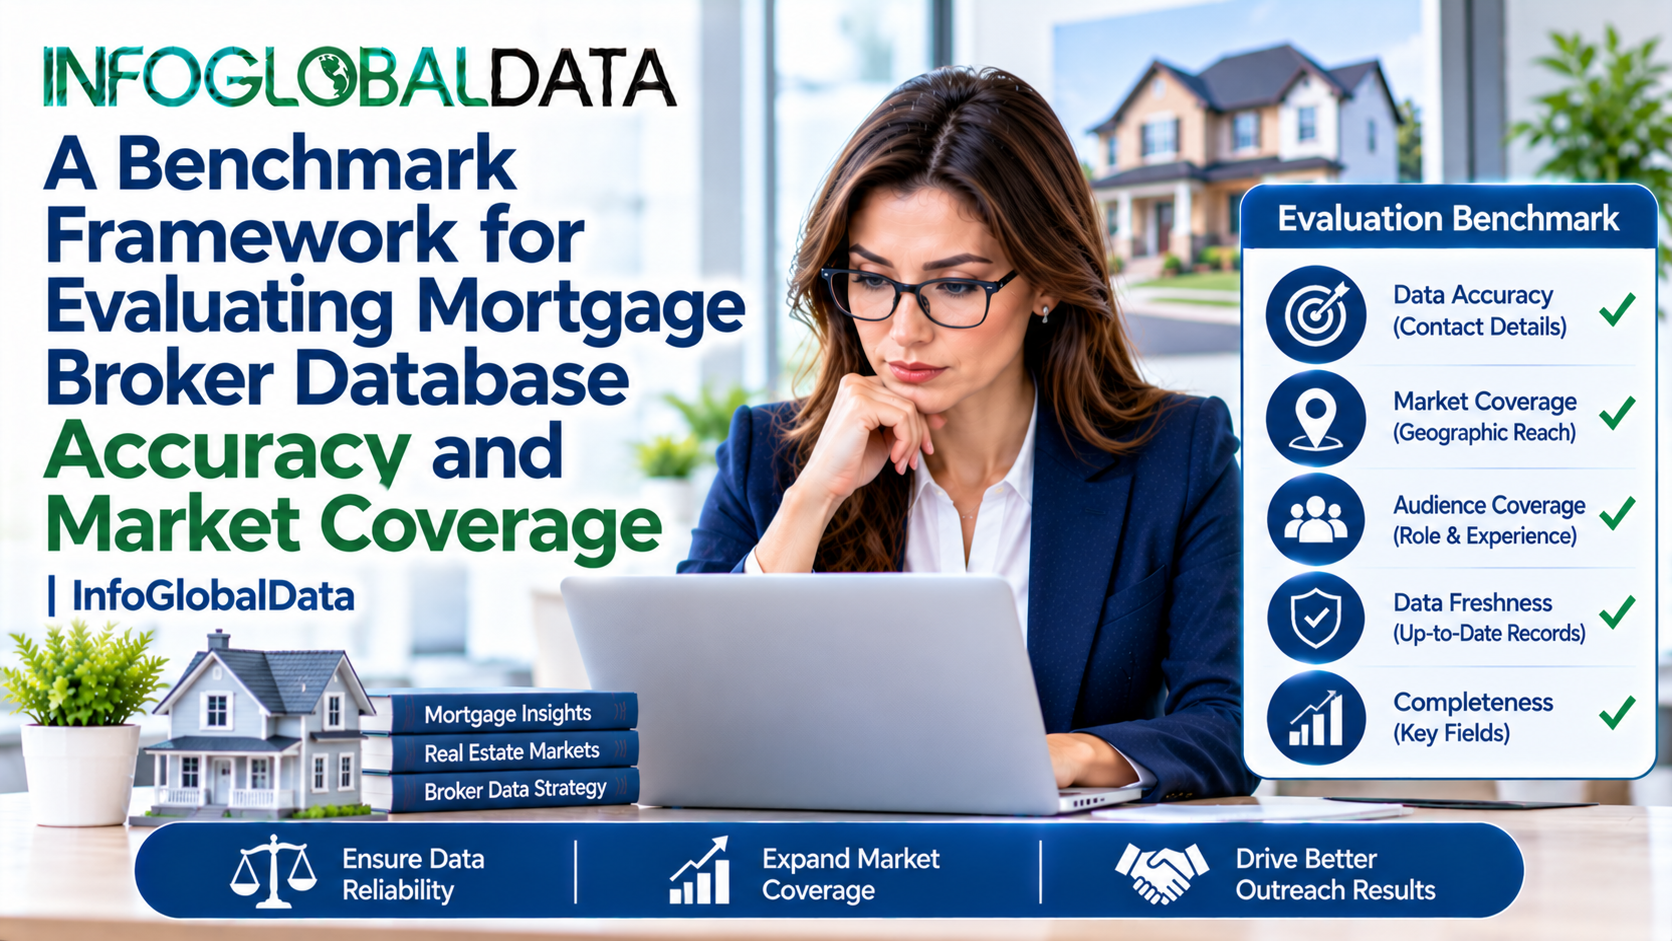
A Benchmark Framework for Evaluating Mortgage Broker Database Accuracy and Market Coverage | InfoGlobalData
Introduction
A mortgage broker database should be evaluated by more than its total number of contacts. Its real value depends on whether records identify active professionals, reflect current company affiliations, cover the right geographic markets, and provide enough detail to support relevant B2B outreach. The market itself is changing: HousingWire, citing mortgage technology platform RETR, reported that the number of producing loan officers at mortgage brokerages increased 12.5% in 2025 to 56,803, even as employment trends differed across other mortgage channels. This movement makes database freshness and channel classification especially important. A dependable Mortgage Broker Email List should therefore be measured against a consistent framework covering contact accuracy, market coverage, role relevance, and update practices—not simply list size.
1. Define What Counts as a Mortgage Broker Contact
Before measuring database quality, establish a clear definition of the audience. Mortgage brokers, mortgage loan officers employed by lenders, loan processors, underwriters, and real estate agents all participate in the home-financing ecosystem, but they are not interchangeable prospects.
A mortgage broker typically works with borrowers and multiple lenders to identify and arrange suitable mortgage financing. A loan officer may work directly for a bank, credit union, or independent mortgage lender. A database that combines these categories without clear labels can inflate its apparent broker coverage.
A useful contact classification should distinguish:
-
Independent mortgage brokers: Professionals operating through brokerage businesses.
-
Brokerage owners and principals: Business decision-makers who may evaluate technology, marketing, and operational services.
-
Producing mortgage loan officers: Originators actively generating mortgage business, with their employment channel identified.
-
Brokerage operations staff: Processors, operations managers, and compliance personnel who may influence workflow-related purchases.
-
Non-broker mortgage professionals: Bank and direct-lender loan officers, clearly separated from broker-channel contacts.
This distinction is important when evaluating a Mortgage Broker Email Database. A large collection of mortgage-related contacts is not necessarily a comprehensive or accurate list of mortgage brokers.
2. Measure Contact Accuracy, Not Just Email Validity
Contact accuracy should be the first major component of a database benchmark. A valid email address only indicates that an address may be capable of receiving messages; it does not confirm the recipient's current role, employer, licensing status, or relevance to a campaign.
Evaluate each record across several fields:
|
Data field |
What to verify |
Why it matters |
|---|---|---|
|
Full name |
Correct spelling and identity |
Prevents misdirected outreach |
|
Job title |
Current role and seniority |
Separates brokers from other mortgage professionals |
|
Company |
Current brokerage or employer |
Supports account-level targeting |
|
Business email |
Domain and address validity |
Reduces avoidable delivery failures |
|
Location |
State, city, or service market |
Enables geographic segmentation |
|
Professional status |
Active, inactive, or unconfirmed |
Helps identify relevant contacts |
|
Update date |
Last review or validation date |
Indicates record freshness |
Where licensing information is relevant, marketers should use appropriate public records and licensing sources to corroborate professional status. In the United States, the Nationwide Multistate Licensing System (NMLS) provides a framework for identifying mortgage industry professionals and companies. However, licensing status alone should not be treated as proof that someone is currently producing loans or operating as an independent broker.
A sound accuracy review should therefore use multiple checks: email validation, employment confirmation, role classification, and relevant professional-status checks.
3. Benchmark Market Coverage by Channel and Geography
A database may contain accurate contacts but still have poor market coverage. For example, it may overrepresent brokers in a few large states while missing smaller markets, independent firms, or professionals working in specialist lending segments.
Mortgage market data can help establish a more realistic coverage benchmark. The Consumer Financial Protection Bureau reported that 2025 Home Mortgage Disclosure Act (HMDA) data covered approximately 4,768 reporting institutions. The data provides a broad view of mortgage lending activity and can help researchers understand lender and geographic patterns. However, HMDA reports lending institutions and loan-level activity—not a complete directory of individual mortgage brokers.
For database evaluation, compare coverage across:
-
State and metropolitan area
-
Independent brokerage versus bank or direct-lender channel
-
Brokerage size and business structure
-
Residential purchase and refinance specialization, where known
-
Conventional, FHA, VA, and other lending specialties, where known
Market coverage should be measured against the intended prospecting audience, not against every organization appearing in mortgage lending statistics. HMDA is useful for market context, but it cannot independently verify an individual broker's email address or professional activity.
4. Use Industry Trends to Test Whether Coverage Is Current
A database benchmark should reflect changes in the mortgage market. Contact records that were accurate several years ago may no longer represent the industry's current employment structure or business opportunities.
HousingWire reported that RETR's preliminary data identified 221,161 producing loan officers across the mortgage industry in 2025, compared with 220,449 in 2024. Within that total, broker-channel loan officer headcount grew 12.5% to 56,803, while loan officer counts at independent mortgage banks and other lenders declined 11.7%. These figures illustrate why a database should identify the channel in which a professional works rather than classify every loan originator as a broker.
Market forecasts also provide context for evaluating geographic and business-segment coverage. In its October 2026 forecast, the Mortgage Bankers Association projected that US single-family mortgage originations would decline 5% in 2027 to just under $2 trillion. It forecast purchase originations of approximately $1.42 trillion and refinance originations of $571 billion.
For database buyers, these trends have two implications:
-
Recheck channel classification: Growth or contraction in different lending channels can make older job and employer classifications less reliable.
-
Review geographic priorities: Market activity varies by location. A database should let users evaluate coverage against the states and metropolitan areas that matter to their business.
A Mortgage Broker Mailing List should be assessed periodically, not treated as a fixed market snapshot.
5. Evaluate Company-Level Coverage and Decision-Maker Depth
Contact volume alone does not reveal whether a database reaches the organizations that matter. A campaign selling CRM software, lead-management tools, compliance services, or marketing technology may need brokerage owners and operations leaders rather than only individual loan originators.
Evaluate whether the database can distinguish:
-
Brokerage owners, founders, and managing partners
-
Branch managers and regional managers
-
Producing brokers and loan originators
-
Operations and processing managers
-
Compliance and risk personnel
-
Marketing and business development leaders
The National Association of REALTORS® 2025 Technology Survey provides useful context for technology-related prospecting across the real estate sector. It found that 36% of respondents said their broker provided their CRM, while 19% purchased CRM technology independently. The survey concerns REALTORS®, not mortgage brokers, so these figures should not be presented as mortgage-broker purchasing behavior. However, they demonstrate why company-level buying arrangements and individual technology decisions can differ across real estate-related professions.
For vendors targeting mortgage brokerages, the practical lesson is to identify both the user and the likely buyer. A producing broker may use a platform daily, while the brokerage owner or operations manager may control the purchase.
6. Build a Weighted Database Quality Scorecard
A consistent scorecard makes it easier to compare providers and identify gaps before purchasing or activating a list. The following is a proposed evaluation framework, not an externally established industry benchmark. Its weights can be adjusted according to campaign objectives.
|
Evaluation category |
Suggested weight |
Questions to assess |
|---|---|---|
|
Contact accuracy |
30% |
Are names, emails, titles, and employers current? |
|
Market coverage |
25% |
Does the database cover target states, cities, and broker channels? |
|
Role relevance |
20% |
Are brokers distinguished from other mortgage professionals? |
|
Company-level depth |
15% |
Are owners, managers, and relevant operational roles represented? |
|
Data transparency |
10% |
Are update practices, validation methods, and data sources explained? |
How to apply the scorecard
Rate each category from 1 to 5:
-
1 – Poor: Major gaps or insufficient evidence.
-
2 – Limited: Some useful records, but substantial weaknesses.
-
3 – Acceptable: Meets basic requirements, with identifiable gaps.
-
4 – Strong: Good coverage and clear validation practices.
-
5 – Excellent: Consistent evidence of accuracy, relevance, and transparent maintenance.
Calculate the weighted score by multiplying each category's rating by its weight and adding the results. For example, a provider with strong contact accuracy but weak geographic coverage may still be unsuitable for a campaign focused on specific states.
Before assigning high scores, request a sample and test it. Check a representative selection of records against public company information, professional profiles, and appropriate licensing records. A provider's claims should be treated as claims to verify, not as independent proof of database quality.
7. Review Data Compliance and Email Deliverability
Database accuracy is only one part of campaign readiness. Marketers must also ensure that contact data is used appropriately and that their email infrastructure meets current sender requirements.
For US commercial email, the Federal Trade Commission's CAN-SPAM guidance requires accurate sender information, non-deceptive subject lines, a valid physical postal address, and a clear opt-out process. These requirements apply to B2B commercial messages as well as consumer marketing.
Google's sender guidelines also require email authentication. All senders to Gmail accounts must configure SPF or DKIM. Bulk senders delivering more than 5,000 messages per day to Gmail accounts must meet additional requirements, including SPF, DKIM, DMARC, and one-click unsubscribe for applicable marketing and subscription messages.
Before activating a Mortgage Broker Email List:
-
Confirm that the data's source and permitted use are understood.
-
Suppress contacts who have opted out.
-
Authenticate the sending domain.
-
Monitor spam complaints and delivery performance.
-
Review applicable privacy and electronic marketing laws in each target market.
A deliverable address does not automatically establish consent or legal suitability for every campaign.
Practical Takeaways for Mortgage Database Buyers
Use these five steps before purchasing or activating a database:
-
Define the audience precisely: Separate independent brokers, brokerage owners, loan officers, and direct-lender employees.
-
Test a sample: Manually check a representative set of records for email validity, current employer, role, and location.
-
Compare geographic coverage: Assess contact distribution against your target states and metropolitan markets rather than relying on total record counts.
-
Evaluate decision-maker depth: Determine whether the database includes owners, branch managers, and operations leaders in addition to producing brokers.
-
Request data transparency: Ask how records are sourced, reviewed, corrected, and updated, and what evidence supports the provider's accuracy claims.
InfoGlobalData offers B2B contact-data and lead-generation resources for sales and marketing teams. Businesses evaluating its Mortgage Broker Email List should apply the same framework to the available contact fields, geographic coverage, role classifications, and data-maintenance practices before deciding whether the records fit their prospecting objectives.
Conclusion
A strong mortgage broker database is not simply a large collection of email addresses. It should accurately identify active professionals, distinguish broker-channel contacts from other mortgage industry roles, and provide sufficient geographic and company-level coverage for targeted outreach. Recent RETR employment data and MBA market forecasts demonstrate why these distinctions matter as mortgage production and workforce patterns change. A structured scorecard covering contact accuracy, market coverage, role relevance, company depth, and transparency gives buyers a more defensible way to compare providers. By testing sample records and reviewing data practices before launch, marketers can reduce targeting waste and build campaigns around a more reliable view of the mortgage broker market.
Frequently Asked Questions
1. What makes a mortgage broker database accurate?
An accurate database contains current professional names, job titles, company affiliations, business email addresses, and location information. It should also distinguish active mortgage brokers from other mortgage professionals and provide transparent information about record validation and updates.
2. How can businesses evaluate a Mortgage Broker Email List?
Evaluate it using contact accuracy, geographic coverage, role relevance, company-level depth, and data transparency. Request a sample and independently check selected records before purchasing or launching a campaign.
3. What is the difference between a mortgage broker and a mortgage loan officer?
A mortgage broker generally works with multiple lenders to help borrowers find financing options. A mortgage loan officer may work directly for a bank, credit union, mortgage lender, or brokerage, so the employment channel should be verified rather than inferred from the job title.
4. Why is geographic coverage important in a Mortgage Broker Mailing List?
Mortgage lending activity and professional coverage vary across states and metropolitan markets. Geographic segmentation helps marketers focus on areas where their products, services, or business partnerships are relevant.
5. What information should a Mortgage Broker Email Database contain?
Useful fields include contact name, current title, brokerage or employer, business email, location, professional category, and record-update information. Company size, branch details, and professional status can provide additional targeting context when available.
6. How often should mortgage broker contact data be updated?
There is no universal update frequency that guarantees accuracy. Businesses should review records before major campaigns and periodically recheck job changes, company affiliations, email validity, and professional status.
7. Can HMDA data be used to verify mortgage broker contacts?
HMDA data provides information about mortgage applications and lending institutions, making it useful for market and geographic analysis. It is not an individual broker directory and cannot independently confirm a broker's current job, email address, or licensing status.